

MPPSC SSE (State Service) · Module 38 · Mains depth · 17 min
The capital market and SEBI
What MPPSC SSE (State Service) asks from this chapter
Syllabus lines this chapter covers:
- Prelims Paper I: General Studies · Economy of India and MP
MPPSC SSE (State Service) has asked 1 question from this chapter (2016); 7 from its whole module.
Read at full depth: basics, the standard layer and the Mains analysis.
Start from zero: owning a small piece of a company
Imagine a popular local sweet shop wants to open ten new branches but needs ₹1 crore. The owner could take a bank loan. Or the owner could invite people to put in money and, in return, own a small part of the business and share its profits.
When a large company does the second thing, it sells shares. If it needs a loan from the public instead, it can issue bonds or debentures. Both are traded in the capital market, which deals in long-term money.
Because ordinary people put their savings into these markets, they need a strong referee. In India that referee is the Securities and Exchange Board of India (SEBI).
How shares are issued and held
Ways to raise money (SEBI's guide):
- IPO (initial public offer): an unlisted company offers shares to the public for the first time, and they get listed on a stock exchange.
- FPO (follow-on public offer): a company that is already listed raises money again from the public.
- Rights issue: a company raises money from its existing shareholders, who can buy new shares in proportion to what they already hold.
- Book building: the company announces a price band. Investors bid within the band, and the final price is set by demand.
Holding shares: the depository system. Earlier, shares were paper certificates that could be lost or forged. Today they are held as electronic records in a depository. This is called dematerialisation, or demat for short.
The players:
- India has two depositories: NSDL (set up in 1996) and CDSL (1999).
- Investors open a demat account with a depository participant (DP), such as a bank or a stockbroker.
SEBI: the market's referee
History. SEBI was set up as a non-statutory body on 12 April 1988 through a government resolution. It got statutory powers under the SEBI Act, 1992, which came into force on 30 January 1992.
Purpose. The preamble of the SEBI Act says SEBI exists:
- To protect the interests of investors in securities.
- To promote the development of the securities market.
- To regulate the securities market.
What it oversees. SEBI regulates the securities market and the intermediaries registered with it. For example, InvITs are trusts registered with SEBI (see Building with private partners: EPC, BOT, HAM, TOT, InvITs and monetisation).
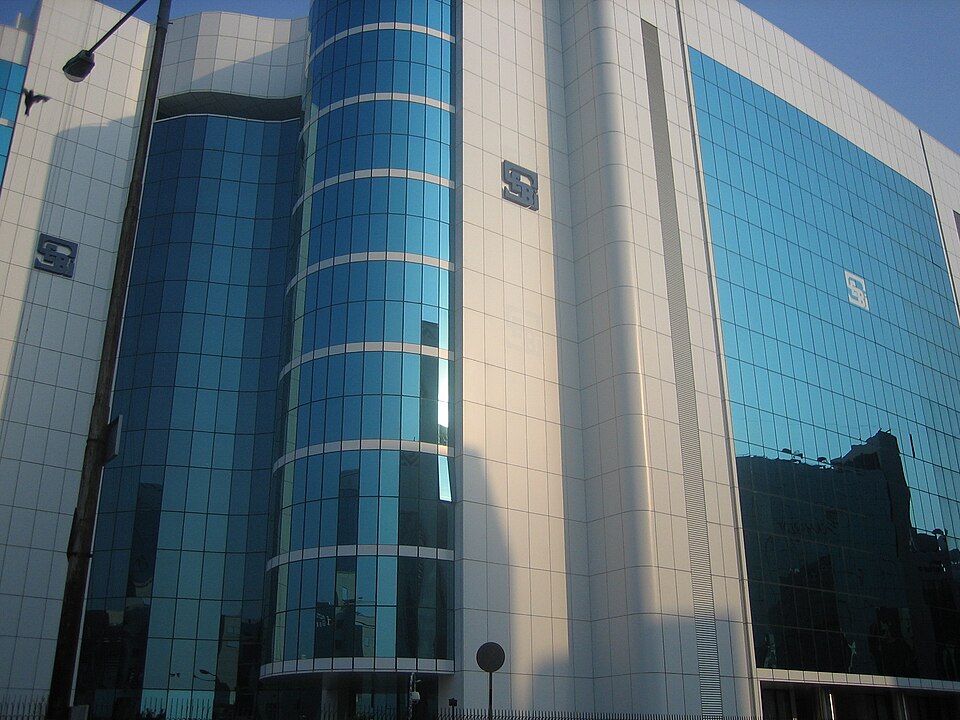
Who regulates what: RBI regulates money markets and G-Secs (see The financial system: money market and government securities); SEBI regulates the securities market. Insurance and pensions have their own regulators.
The retail investor wave
The numbers (Economic Survey 2025-26):
- Demat accounts crossed 21.6 crore by December 2025, with 235 lakh added in FY26 till December.
- Unique demat investors crossed 12 crore in September 2025, and nearly a fourth of them are women.
- Mutual funds had 5.9 crore unique investors at the end of December 2025.
- SIP (systematic investment plan) flows averaged under ₹4,000 crore a month in FY17 and over ₹28,000 crore in FY26 (April-November).
- Equity and mutual funds rose from 2% of household financial savings in FY12 to over 15.2% in FY25.
New investor-friendly steps (2025): SEBI introduced 'Chhoti SIP' of just ₹250. It also launched 'SEBI Check' from 1 October 2025, so investors can verify the UPI IDs of registered intermediaries before paying.
Why this matters: more household savings are flowing into productive companies instead of gold or idle cash. But new investors also face risks from market falls and fraud, which makes SEBI's role more important.
Futures and options: why most small traders lose
Start with a promise about a future price. A farmer and a miller agree today that the miller will buy wheat in three months at a fixed price. Whatever happens to the market price, both know what they will pay and receive. This is the old idea behind derivatives: contracts whose value comes from something else, such as a share, an index or a crop.
Futures and options. A future is a contract to buy or sell at a fixed price on a future date. An option gives the buyer the right, but not the duty, to buy or sell at a fixed price, in return for a small payment called the premium. Firms and big investors use these tools to hedge, that is, to protect themselves from price swings.
What went wrong for small traders. Because options need only a small premium, many young investors began to use them as a quick bet rather than as protection. A SEBI study found that 93% of over 1 crore individual traders in equity F&O lost money between FY22 and FY24. Their losses averaged about ₹2 lakh per trader, including transaction costs, and added up to more than ₹1.8 lakh crore.
Who was losing. In FY24, more than 75% of these traders had declared an annual income below ₹5 lakh. Traders below 30 years of age rose from 31% to 43% of the total in one year. Even so, more than three-quarters of those who lost money kept trading.
Why SEBI worries. Household savings that could fund businesses were instead being lost in short-term bets, often to large algorithmic traders. SEBI made the study public so that investors and policymakers could see the scale of these losses. A good Mains answer separates healthy hedging from speculation and links investor protection to financial literacy.
T+1: faster settlement, safer markets
Start with buying a share on Monday. When you buy a share, you pay money and the seller hands over the share, but this exchange does not happen at the moment of the trade. It is completed a little later through the clearing and settlement system. The time between the trade and this final exchange is called the settlement cycle.
From T+2 to T+1. In a T+1 cycle, settlement happens one working day after the trade day, which is called "T". India moved to T+1 in phases, starting in November 2021 and completing the change in January 2023. This made India one of the earliest adopters of T+1 among the world's securities markets.
Why faster settlement matters. While a trade is unsettled, either side might fail to pay or deliver, so brokers and clearing houses must keep money aside as a safety margin. A shorter cycle means less time for things to go wrong and less money locked up as margin. Investors also get their shares or sale money sooner.
How the demat system made it possible. Settlement this fast would be impossible with paper share certificates. It works because shares are held in electronic form in demat accounts with depositories, and money moves through electronic banking. Technology built over three decades thus allowed a big jump in market safety.
The Mains angle. T+1 shows how market plumbing, not only market rules, protects investors. A good answer links it to lower systemic risk, better liquidity and India's ambition to become a global financial centre. It can also mention that foreign investors had to adjust their currency and operational timelines.
How the stock market was rebuilt after 1992
Picture the market in 1990. Brokers shouted prices on a crowded trading floor in Mumbai. Shares existed as paper certificates that were posted, signed and often lost or forged. A deal could take weeks to settle, and a small investor in a small town might deal through several middlemen.
The old rules. Under the Capital Issues (Control) Act, 1947, a company needed government approval for how many shares to issue and at what price. The Bombay Stock Exchange, trading formally since 1875, was run by brokers. Settlement was fortnightly, and badla let traders carry positions forward without paying.
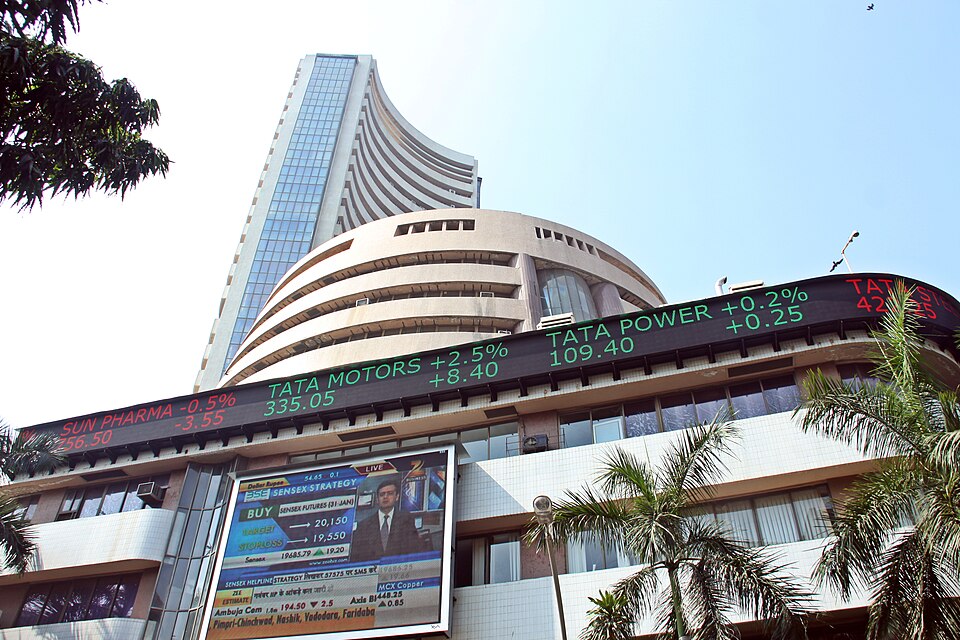
The shock of 1992. In 1992, the Harshad Mehta scam exposed how weak settlement in government bonds could be misused to pump money into shares. The same year, the old issue controls were repealed and SEBI, set up in 1988, got statutory powers. Reform after this came quickly, often pushed by crises.
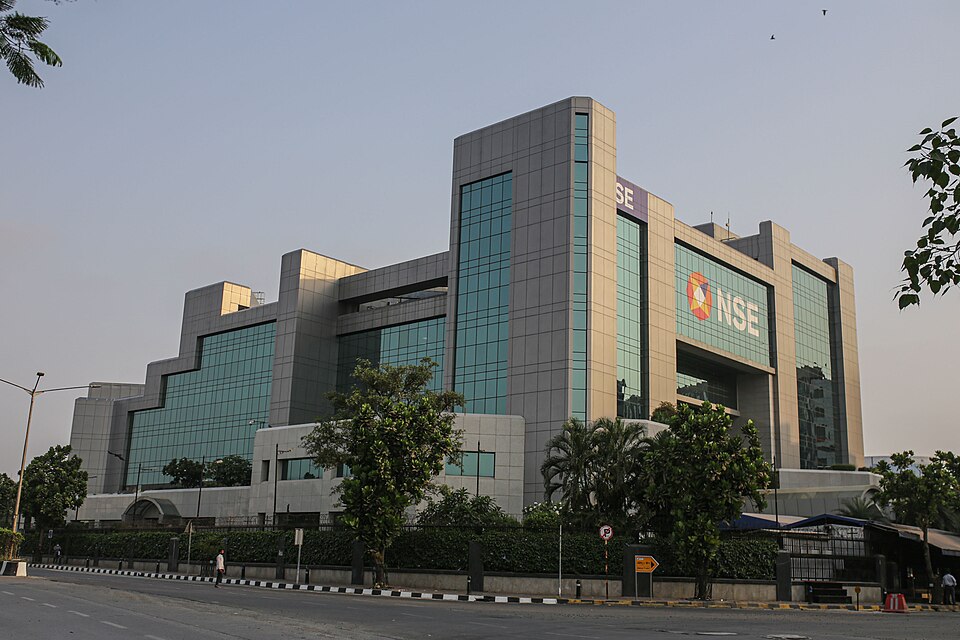
The rebuild, step by step.
- National Stock Exchange (1994): began equity trading in November 1994 with nationwide screen-based trading, so prices became transparent; the BSE moved to screens in 1995.
- Clearing corporation (1996): NSCCL began guaranteeing every trade through novation, so one party's default would not sink the other.
- Depositories Act (1996): NSDL and CDSL let shares be held in demat form, ending bad deliveries and forged certificates.
- Derivatives (2000): index futures began in June 2000, after a long ban on forward trading was lifted.
- Rolling settlement (2001): badla was banned and all shares moved to rolling settlement, the base for today's T+1.
Why this matters for answers. India's market went from one of the least transparent to one with world-class trading systems within a decade. Each step answered a specific failure, which is a good way to explain the role of regulation in Mains.
Why the capital market needs a watchdog: when, where and why
Why a capital market? Companies need long-term money to build factories and grow, and households want their savings to earn more than a bank deposit. By selling shares and bonds, a company raises funds from many small investors at once. This is how savings turn into investment.
Why a regulator? A company knows far more about itself than an outside investor does, so investors can be misled or cheated. Without trust, people stop investing and the market dries up. So SEBI, set up in 1988 and made statutory by the SEBI Act, 1992, exists to protect investors and to promote and regulate the securities market.
Why demat? Paper share certificates could be lost, forged or delayed in transfer. Depositories (NSDL, 1996, and CDSL, 1999) hold shares in electronic form, which makes trading faster and safer.
Implications. Trust has brought ordinary households in: demat accounts crossed 21.6 crore by December 2025, and monthly SIP flows rose from under ₹4,000 crore in FY17 to over ₹28,000 crore in FY26. More small investors also means more people exposed to market risk, which is why SEBI keeps adding safeguards such as SEBI Check.
Mains lens: deepening markets, protecting investors
1. Benefits. A deep capital market gives firms long-term funds, spreads ownership of companies and helps households build wealth. It also reduces the economy's dependence on bank loans.
2. Risks.
- Speculation: new investors may trade in risky products without full understanding.
- Fraud: fake advisers and unregistered "tips" can mislead people.
- Reach: participation is spreading; 3.5 crore mutual fund investors came from beyond the top cities (November 2025), but financial literacy remains uneven.
3. The regulator's balance. SEBI must protect investors without choking the market's growth. Steps like small-ticket SIPs, faster settlement and verification tools aim at both.
A good conclusion: India's capital market has become far more retail and digital. Its long-term health depends on financial literacy, strong regulation and trust.
Mains practice: three questions, three angles
These are practice questions written by us, not past papers. Past questions from each exam are in the PYQ panel of this module.
| Angle | Question | Key points to cover |
|---|---|---|
| Why (origin) | Why was SEBI given statutory powers? Examine its role in investor protection. | Trace the 1988 resolution and the SEBI Act of 1992. Then explain the information gap between companies and investors, and SEBI's job to protect, develop and regulate. |
| Trend | Rising retail participation in equity markets: opportunity or risk? Discuss. | Use the 21.6 crore demat accounts and the growth of SIPs as evidence. Then explain the shift in household savings and the need for investor education. |
| Concept | Distinguish between the primary and secondary markets with examples of IPO, FPO and rights issue. | Contrast a new issue of shares with the trading of existing ones. Then explain book building and listing. |
How to use this table: each answer should explain the what, then the why from the section above, and end with a way forward.
Quick revision
- SEBI was set up as a non-statutory body on 12 April 1988 and became statutory under the SEBI Act, 1992 (in force from 30 January 1992).
- Its job is to protect investors and to develop and regulate the securities market.
- An IPO is an unlisted company's first public issue, an FPO is a further issue by a listed company, and a rights issue offers new shares to existing shareholders first.
- In book building, investors bid within a price band, and the final price is found from their bids.
- India's two depositories are NSDL (1996) and CDSL (1999), and investors open demat accounts through their depository participants.
- The Economic Survey 2025-26 counts more than 21.6 crore demat accounts and more than 12 crore unique investors, about a quarter of them women, along with 5.9 crore mutual fund investors.
- Monthly SIP flows grew from under ₹4,000 crore to over ₹28,000 crore, and equity and mutual funds rose from 2% to 15.2% of household financial savings.
- In 2025, SEBI introduced a "Chhoti SIP" of ₹250 for small savers and SEBI Check to verify the UPI IDs of registered intermediaries.
- SEBI study (2024): 93% of over 1 crore individual equity F&O traders lost money in FY22-FY24, about ₹2 lakh each, over ₹1.8 lakh crore in all.
- T+1 settlement (one working day after trade) was completed in January 2023; India was among the earliest adopters.
- Rebuild after 1992 (Harshad Mehta scam; CCI Act 1947 repealed; SEBI statutory): NSE screen trading Nov 1994, NSCCL novation 1996, Depositories Act 1996 (NSDL, CDSL, demat), derivatives June 2000, badla ended, rolling settlement 2001.
Common confusions and exam traps:
- SEBI began in 1988 but became statutory only in 1992.
- Money markets and G-Secs are regulated by RBI, not SEBI.
- A rights issue is offered to existing shareholders, not the public.
MPPSC SSE (State Service) questions from this chapter
Which one of the following is irrelevant in the context of share market?
- (a) Sensex
- (b) BSE
- (c) Nifty
- (d) SAPS
Show answer
(d) SAPS · our answer; official key awaited