

RPSC RAS / RTS · Module 46 · Mains depth · 15 min
Disinvestment, privatisation and asset monetisation
What RPSC RAS / RTS asks from this chapter
Syllabus lines this chapter covers:
- General Knowledge and General Science · Agricultural development and reforms; industrial growth, policy and LPG reforms; service sector, energy, transport and communication; skill development, employment, social justice and empowerment.
- General Studies I · Industry policy and reforms, LPG, industrial finance and MSMEs; services and infrastructure; international trade, balance of payments, foreign aid and investment.
RPSC RAS / RTS questions from this module are being sorted into our bank.
Read at full depth: basics, the standard layer and the Mains analysis.
Start from zero: when the government sells a business
Start with a family shop. Imagine a family that owns ten shops, but has little time to run them and needs money for the children's education. It could sell a few shares in each shop and keep control, sell some shops outright, or rent them out for a few years. The government faces the same choices with the companies it owns.
The words to know. The government owns many Central Public Sector Enterprises (CPSEs). Selling part of its stake is called disinvestment, and DIPAM divides it into two kinds:
- Minority stake sale: the government sells some shares but keeps control, through an IPO, an FPO, an offer for sale (OFS) on the stock exchange, a buyback, or an exchange traded fund (ETF).
- Strategic disinvestment: the government sells all or a large part of its stake along with management control. When control goes to a private buyer, this is privatisation.
A third route: monetisation. Under asset monetisation, the government does not sell the asset at all. It leases a road, a railway line or a power line to a private operator for a fixed period and gets money upfront, and the asset comes back at the end.
Why India built public enterprises, and why it began to sell
Why the state built them. At Independence, private capital was scarce and risk-averse. Steel plants, heavy machinery, oil exploration and power needed huge, long-term investment that few private firms could make. The 1956 Industrial Policy Resolution gave the state the "commanding heights", and public enterprises also aimed at regional balance, jobs and self-reliance (see Industrial policy: from 1948 to 1991 and after).
What went wrong. By the 1980s, many public enterprises suffered from project delays, over-capitalisation, overstaffing, under-used capacity and political interference. Returns on the huge capital invested were low, and loss-making units drained the budget. The 1991 Industrial Policy itself admitted these problems.
Why selling made sense in 1991. The government was short of money during the 1991 crisis, and its businesses had locked up public capital. Selling shares could raise funds, bring market discipline through listing, and let the state focus on areas where markets do not work well. Critics, however, warned against selling profitable units cheaply to fill budget gaps, which they called "deficit privatisation".
Thirty years of disinvestment
The first phase (1991-1999). Disinvestment began in 1991-92, when the government sold minority stakes in several CPSEs and raised ₹3,038 crore. Control stayed with the government. A Disinvestment Commission was set up on 23 August 1996 under G.V. Ramakrishna to advise on which companies to sell and how.
Strategic sales (1999-2004). A separate Department of Disinvestment was created on 10 December 1999, and India adopted strategic sale as policy. The first was Modern Food Industries, where 74% went to Hindustan Lever. BALCO followed, with 51% sold to Sterlite for ₹551.50 crore on 2 March 2001, and stakes in VSNL, Hindustan Zinc, IPCL and Maruti Udyog were also sold.
A pause and a new fund (2004-2014). The department became part of the Finance Ministry in 2004, and big strategic sales slowed. From 1 April 2005, proceeds were to go to a National Investment Fund, whose income would support social sector schemes and capital investment in public enterprises. Minority sales through public offers continued.
The recent phase (2014 onwards). New tools such as the CPSE ETF (2014) and Bharat-22 ETF (2017) spread public shares among small investors. The department was renamed DIPAM on 14 April 2016, and receipts hit a record of about ₹1 lakh crore in 2017-18. Air India was sold to Talace (Tata Sons) on 27 January 2022, and the LIC IPO of May 2022 raised about ₹20,516 crore.
The New Public Sector Enterprise Policy (2021)
The big shift. For decades, the question was how much of a public company to sell. The New Public Sector Enterprise Policy, announced in the Budget of 1 February 2021, asked a different question: in which sectors should the state be present at all? It divides the economy into strategic and non-strategic sectors.
The four strategic sector groups.
- Atomic energy, space and defence
- Transport and telecommunications
- Power, petroleum, coal and other minerals
- Banking, insurance and financial services
What happens to each. In strategic sectors, the government keeps a bare minimum presence of public enterprises at holding company level. The May 2020 announcement said this would ordinarily mean only one to four enterprises per sector. In non-strategic sectors, CPSEs are to be privatised, or closed if no buyer is found.
The policy at work. Air India (2022) and Neelachal Ispat Nigam (sold to Tata Steel Long Products in 2022) showed that strategic sales could be completed. On 14 October 2026, the Cabinet Committee on Economic Affairs approved a company of the Fairfax group as the buyer of 60.72% of IDBI Bank at ₹81 a share, worth about ₹52,878 crore. The sale still needs the RBI's approval of the buyer as fit and proper.
Receipts and asset monetisation
How much has been raised. Disinvestment receipts swing a lot from year to year, because they depend on market conditions and on whether big sales close. They touched a record of about ₹1 lakh crore in 2017-18, but fell to about ₹10,163 crore in 2024-25 and ₹16,886 crore in 2025-26. Targets have often been missed, which makes them an unreliable source for the budget.
How the budget shows it. In the budget, these receipts sit under "miscellaneous capital receipts", which also include asset monetisation. This head is budgeted at ₹80,000 crore for 2026-27. Because they are non-debt capital receipts, they reduce how much the government must borrow (see Deficits and debt: fiscal, revenue and primary deficit, and the FRBM Act).
Asset monetisation. Instead of selling companies, the government can lease brownfield assets, those already built and earning, such as highways, railway stations, power lines and pipelines. The private operator pays upfront or shares revenue, runs the asset for a fixed period, and returns it. The money is then used to build new infrastructure, which is why the idea is often called recycling capital.
The pipelines. The first National Monetisation Pipeline, launched on 23 August 2021, estimated about ₹6 lakh crore over four years and achieved nearly 90%. NMP 2.0, launched on 23 February 2026, estimates ₹16.72 lakh crore over 2025-26 to 2029-30, led by highways, power, railways, ports and coal.
Inside the deals: fixing, selling and spreading shares
Fix first, or sell? The 1991 reforms did not only sell shares. Chronically sick public enterprises were referred to the Board for Industrial and Financial Reconstruction (BIFR) to decide whether they could be revived or should close. Healthy ones signed Memoranda of Understanding (MoUs) with their ministries, which gave managers more freedom in return for clear yearly targets. The idea was that a public firm should be judged on results, like a private one.
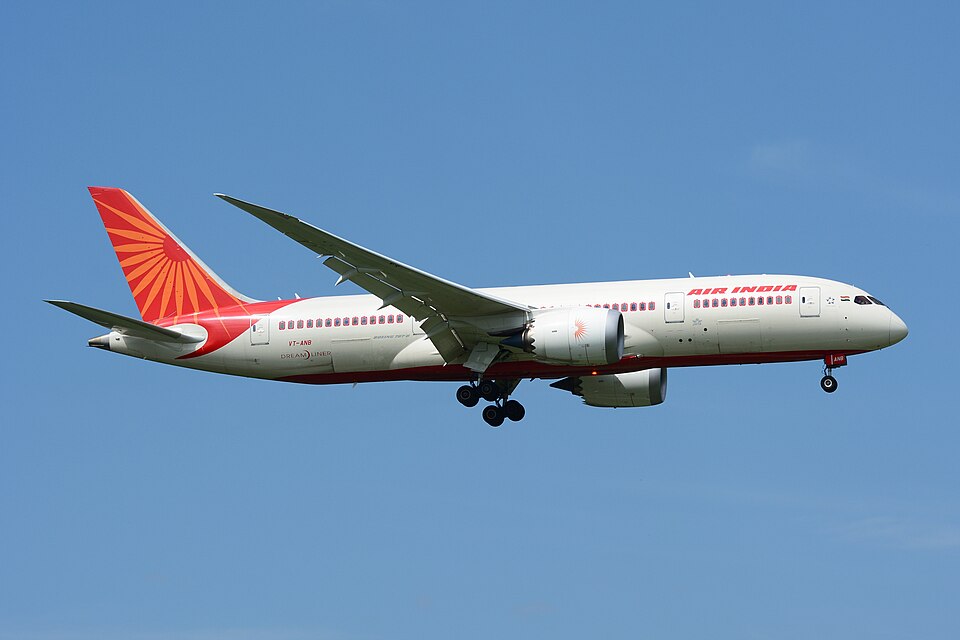
Anatomy of the Air India sale. Air India had piled up large debts and needed regular support from the budget. When it was sold to Talace, a Tata Sons company, in January 2022, the government received ₹2,700 crore in cash, while ₹15,300 crore of the airline's debt stayed with the airline under its new owner. This shows a key lesson: the value of a sale is not only the cash received, but also the future losses and debts the state no longer has to carry.
Spreading shares among citizens. Minority sales are also a way to let ordinary people own public firms. The CPSE ETF (2014) and the Bharat-22 ETF (2017), whose first issue raised ₹14,500 crore, bundle shares of many CPSEs into one product that small investors can buy. The LIC IPO of 2022 was the largest in India's history, and a later offer for sale in LIC raised about ₹31,515 crore in 2026-27.
Why this matters. Listing forces companies to publish results every quarter and answer to shareholders. It also gives the government a market price for its stake, which makes later sales easier to value. A minority sale can therefore be a step towards better governance even when control stays with the state.
Why sell at all? The debate
The case for. Supporters say private owners run firms more efficiently because they face profit pressure and hard budgets. Sales free public money for schools, health and roads, and listing makes companies more transparent. Air India, which had lost money for years, is often cited as a firm that the state should never have kept running.
The case against. Critics say profitable public firms are sold to fill short-term budget gaps, sometimes at low prices. Public enterprises also serve social goals, such as jobs for reserved categories, services in remote areas and stable prices in a crisis. Selling to a single buyer can create a private monopoly unless regulation is strong.
Where the middle ground lies. Most economists agree that the state should keep what markets cannot provide well and exit businesses such as hotels or bakeries. They also stress how sales are done: transparent valuation, competitive bids, protection for workers, and use of proceeds for new assets rather than daily spending. The 2021 policy tries to follow this logic by naming strategic sectors in advance.
Implications. Disinvestment links to fiscal policy, because it is a non-debt receipt; to industrial policy, because it reshapes the public sector; and to governance, because it needs clean, open processes. A good Mains answer weighs efficiency against social goals and ends with safeguards.
Mains practice: four questions, four angles
These are practice questions written by us, not past papers. Past questions from each exam are in the PYQ panel of this module.
| Angle | Question | Key points to cover |
|---|---|---|
| Why (origin) | Why did India build a large public sector after Independence, and why did it start disinvestment after 1991? | Scarce capital, commanding heights, 1956 IPR; problems: delays, overstaffing, low returns; 1991 crisis; first sale 1991-92 (₹3,038 crore). |
| Policy | Examine the New Public Sector Enterprise Policy of 2021. How does it change the logic of disinvestment? | Four strategic sector groups, bare minimum presence, privatise or close in others; Air India, NINL, IDBI Bank; from stake sale to exit. |
| Fiscal | "Disinvestment should fund new assets, not fill fiscal gaps." Discuss. | Non-debt capital receipt; record ~₹1 lakh crore 2017-18 vs ~₹10,163 crore 2024-25; deficit privatisation; National Investment Fund; misc. capital receipts BE ₹80,000 crore 2026-27. |
| Way forward | Is asset monetisation a better alternative to privatisation for infrastructure? Examine with reference to NMP 2.0. | Brownfield leasing, ownership retained, recycling capital; NMP 1.0 ~₹6 lakh crore, ~90% achieved; NMP 2.0 ₹16.72 lakh crore; risks: valuation, user charges, contract design. |
How to use this table: each answer should explain the what, then the why from the sections above, and end with a way forward.
Quick revision
- Minority stake sale keeps government control (IPO, FPO, OFS, buyback, ETF); strategic disinvestment transfers control; asset monetisation leases assets without selling them.
- Disinvestment began in 1991-92 (₹3,038 crore); Disinvestment Commission 23 Aug 1996 (G.V. Ramakrishna); Department of Disinvestment 1999; DIPAM from 14 Apr 2016.
- Strategic sales: Modern Food (74% to Hindustan Lever), BALCO (51% to Sterlite, 2 Mar 2001); National Investment Fund from 1 Apr 2005; CPSE ETF 2014, Bharat-22 2017.
- New PSE Policy (Feb 2021): four strategic groups (atomic energy/space/defence; transport/telecom; power/petroleum/coal/minerals; banking/insurance/finance) with bare minimum presence; others privatised or closed.
- Air India to Talace (Tata) on 27 Jan 2022; LIC IPO May 2022 (~₹20,516 crore); IDBI Bank 60.72% to a Fairfax company approved 14 Oct 2026, awaiting RBI.
- Receipts: record ~₹1 lakh crore (2017-18); ~₹10,163 crore (2024-25); misc. capital receipts BE ₹80,000 crore (2026-27).
- NMP 1.0 (Aug 2021) ~₹6 lakh crore, ~90% achieved; NMP 2.0 (Feb 2026) ₹16.72 lakh crore for 2025-30.