

UPSC IES / ISS · Module 37 · standard depth · 11 min
Financial inclusion: Jan Dhan, MUDRA and beyond
What UPSC IES / ISS asks from this chapter
Syllabus lines this chapter covers:
- IES: General Economics II · Financial and Capital Market
- IES: Indian Economics · Money and Banking
UPSC IES / ISS questions from this module are being sorted into our bank.
Cut to standard depth for UPSC IES / ISS. 7 deeper paragraphs are in the full chapter.
Start from zero: the vegetable seller and the moneylender
Think of a woman who sells vegetables from a cart. Every morning she needs ₹2,000 to buy stock from the mandi. With no bank account, she borrows from a moneylender at very high interest, and much of her profit goes to him.
Now imagine she has a bank account. Her savings are safe, government benefits reach her directly, and the bank knows her payment record. Later, she can get a small business loan at a fair rate.
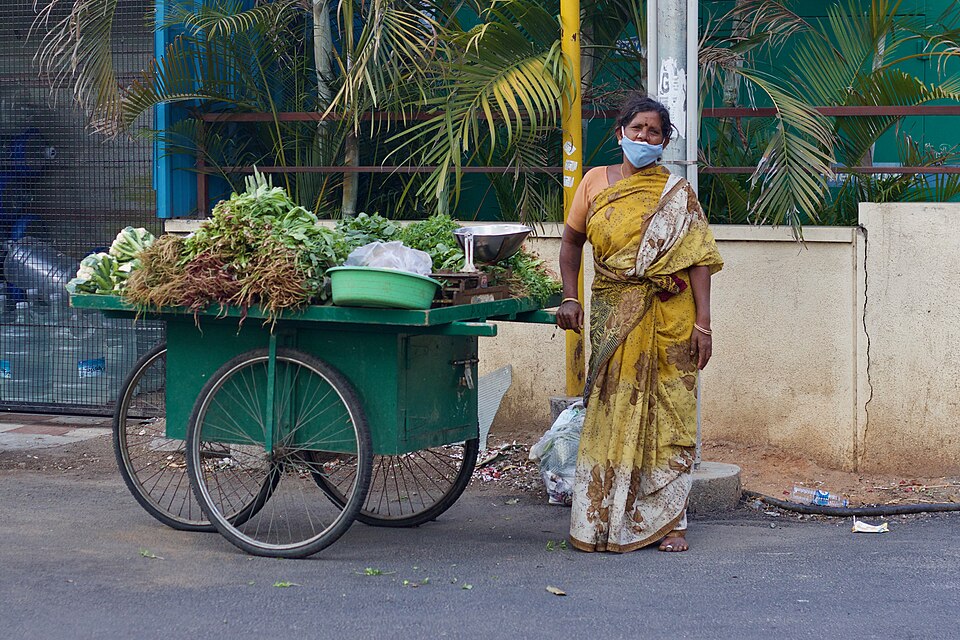
This is financial inclusion: making sure everyone, especially the poor, can use basic financial services such as a bank account, credit, insurance and pensions at affordable cost.
Pradhan Mantri Jan Dhan Yojana
The launch. PMJDY was launched on 28 August 2014 as the National Mission for Financial Inclusion. The government calls it the world's largest financial inclusion initiative.
Features of a Jan Dhan account:
- No minimum balance requirement and no maintenance charges.
- A free RuPay debit card with accident insurance cover of ₹2 lakh.
- An overdraft facility of up to ₹10,000.
The reach (as on 19 August 2026):
| Indicator | Value |
|---|---|
| Total accounts | 59.09 crore |
| Women's share | About 56% (32.92 crore) |
| Rural and semi-urban share | About 78% (45.95 crore) |
| Deposits | ₹3.17 lakh crore |
| RuPay cards issued | 41.29 crore |
The bigger picture: Jan Dhan accounts are the "J" in the JAM trinity with Aadhaar and mobile, which the government calls a diversion-proof way to deliver benefits through DBT (see Inclusive growth and welfare: DBT, social security and rural jobs).
MUDRA: loans for the smallest businesses
The scheme. Pradhan Mantri MUDRA Yojana (PMMY) was launched on 8 April 2015. It gives collateral-free loans to micro enterprises. Think, for example, of a small shop or a tailoring unit.
Four categories:
- Shishu: up to ₹50,000.
- Kishor: above ₹50,000 and up to ₹5 lakh.
- Tarun: above ₹5 lakh and up to ₹10 lakh.
- Tarun Plus: above ₹10 lakh and up to ₹20 lakh (started in 2024).
Who lends. MUDRA itself does not lend to borrowers. It gives refinance support to lending institutions, including scheduled commercial banks, regional rural banks, small finance banks, NBFCs and microfinance institutions. These institutions lend directly.
The reach (as on 27 March 2026). Over ₹40.07 lakh crore has been disbursed through 57.79 crore loans. About two-thirds of the loans went to women. Shishu loans are 74% of all loans by number, but only 32% by amount.
The full inclusion ladder
Financial inclusion is not just one account. It is a ladder of services:
| Step | Need | Main scheme |
|---|---|---|
| 1 | A safe place to save and receive money | Jan Dhan account |
| 2 | Direct receipt of benefits | DBT via JAM |
| 3 | Small business credit | MUDRA |
| 4 | Protection against shocks | RuPay cards carry accident cover, and low-cost insurance gives wider protection. |
| 5 | Income in old age | Atal Pension Yojana |
| 6 | Fast, cheap payments | UPI |
Why this matters: each step builds on the last. An account allows benefits, a payment record allows credit, and credit allows a business to grow.
Measuring inclusion: the FI-Index
Start with a bank account that is never used. A woman opens a bank account in a camp, gets a card and goes home. If she never deposits money, never makes a payment and never takes a loan, is she really included in the financial system? Counting accounts alone cannot answer that question, so India needed a broader measure.
What the FI-Index is. The Reserve Bank of India launched the Financial Inclusion Index (FI-Index) in 2021. It scores the country on a scale from 0 to 100, where 0 means total exclusion and 100 means full inclusion. It combines 97 indicators covering banking, insurance, investments, pensions and postal services.
Three parts, three weights. Access measures whether services are within reach, such as branches, ATMs and accounts, and carries 35% weight. Usage measures whether people actually use them, such as deposits, loans and payments, and carries the highest weight of 45%. Quality covers financial literacy, consumer protection and fair service, and carries 20%.
Why usage gets the biggest weight. India has largely solved the access problem through Jan Dhan accounts, Aadhaar and mobile phones. The harder task now is to make people save, borrow, insure and pay through these accounts. By giving usage the highest weight, the index rewards real use over mere opening of accounts.
The trend. The FI-Index rose to 67.0 in March 2025, from 64.2 in March 2024. RBI said the gain came mainly from better usage and quality, with improvement in all three sub-indices. A good Mains answer uses this to argue that India is moving from access to use, but still has a long way to go.
Microfinance: lending without collateral
Start with a tailor who has no land. A woman wants ₹20,000 to buy a sewing machine and start stitching clothes. She has no land, no salary slip and no credit history, so a bank sees her as too risky. Microfinance was invented to lend to exactly such people.
How it works. Microfinance lenders give small loans, often to women, usually through groups. In many models the members of a group are jointly responsible, so if one member fails to repay, the others feel pressure to help. This peer pressure and close knowledge of each other replace the collateral that a bank would normally ask for.
Why it matters. Small loans let poor families start a shop, buy a cow or handle a medical emergency without going to a moneylender. Because repayments are weekly or monthly and small, they fit the cash flows of daily earners. Microfinance also brings many women into formal credit for the first time.
Where it goes wrong. When several lenders give loans to the same borrower, she may borrow from one to repay another and fall into a debt trap. High interest rates and pressure for collection can hurt the very people the system is meant to help. For this reason regulators watch the total debt of a household and the way loans are recovered.
The link to MUDRA. The smallest MUDRA loans, Shishu, reach the same group of tiny businesses, and MUDRA refinances microfinance institutions among other lenders. A good Mains answer sees microfinance as a bridge from the moneylender to the bank, but one that needs careful rules against over-lending.
Why financial inclusion became a mission: when, where and why
The problem: people outside the system. A family without a bank account keeps cash at home, borrows from moneylenders at high interest and cannot easily receive government help. A small shopkeeper without collateral or records cannot get a bank loan, however good the business. Exclusion keeps the poor poor.
Step one: an account for everyone (2014). PMJDY, launched on 28 August 2014, aimed to bring the underprivileged in far-flung areas into the formal financial sector, so that every unbanked adult has a basic account. With no minimum balance, a RuPay card and insurance cover, it removed the usual reasons for staying out.
Step two: credit for the small (2015). Micro enterprises had long been held back by limited access to bank credit, since they often lacked collateral and formal records. MUDRA (8 April 2015) answers this with collateral-free loans, under the vision "Funding the Unfunded". It refinances banks and other lenders rather than lending directly.
Implications. Accounts linked with Aadhaar and mobile, the JAM trinity, let the government send money straight to people, which the government calls a diversion-proof mechanism. The next challenge is use: keeping accounts active, making credit affordable and teaching people to save and insure.
Quick revision
- PMJDY was launched on 28 August 2014, and by 19 August 2026 it had opened 59.09 crore accounts.
- About 56% of these accounts belong to women and about 78% are in rural or semi-urban areas, holding deposits of ₹3.17 lakh crore with 41.29 crore RuPay cards issued.
- A Jan Dhan account needs no minimum balance, and it comes with ₹2 lakh of accident cover on the RuPay card and an overdraft of up to ₹10,000.
- PMMY (MUDRA) began on 8 April 2015 to give collateral-free loans to small businesses.
- Its loans come in four sizes: Shishu up to ₹50,000, Kishor up to ₹5 lakh, Tarun up to ₹10 lakh, and Tarun Plus up to ₹20 lakh (added in 2024).
- By 27 March 2026, 57.79 crore MUDRA loans worth ₹40.07 lakh crore had been given, about two-thirds to women, and Shishu loans were 74% by number.
- MUDRA itself does not lend to borrowers, because it refinances the banks, RRBs, small finance banks, NBFCs and MFIs that do.
- RBI's FI-Index (0-100; Access 35%, Usage 45%, Quality 20%) rose to 67.0 in March 2025 from 64.2, led by usage and quality.
- Microfinance lends small sums without collateral through group responsibility; its main risk is over-indebtedness.
Common confusions and exam traps:
- MUDRA is a refinancing body; it does not lend directly to borrowers.
- The Jan Dhan overdraft is ₹10,000; the RuPay accident cover is ₹2 lakh.
- Tarun Plus (up to ₹20 lakh) is the newest category, started in 2024.